Credit Score Education
 Credit Reporting & Consumer Rights
 Personal Finance Tips
 Budgeting & Money Management
 Identity Theft & Fraud Prevention
 Credit Card Education
 Consumer Financial News
 Cost of Living & Inflation
 Banking & Savings Education
 Consumer Protection & Financial Literacy

A paycheck that arrives once a month can make the calendar feel different fast. Rent may be due before payday, and the deposit may look large even though it has to cover several weeks of spending. The key change is timing: build the plan around money you can count on, then map each bill and everyday cost to the date that money needs to last until.
Start with take-home pay, not the offer letter
Use the net amount that reaches your account after taxes and deductions. A pay stub shows that figure, while gross pay does not account for withholdings. For a steadier estimate, add up a full year of take-home pay and divide by 12. That gives you a monthly planning number based on the year, rather than on how many deposit dates happen to fall in one calendar month. The paycheck budgeting guide describes this approach.
If you are moving from weekly pay, the annual calculation may be more useful than multiplying one check by four. A year has 52 weeks, so four weekly checks do not represent a full year of weekly pay. If your hours or check amounts vary, use a cautious estimate based on income you can reasonably count on, not your best week. Keep overtime, bonuses, and side income outside the core budget until the money arrives. Extra income can then be assigned to a goal, such as savings or debt payments, without making essential bills depend on it.
For example, if weekly take-home pay is usually similar, total the year’s expected net pay and divide by 12. If the amount changes with hours, a lower, dependable estimate may be more workable. Either way, write down the assumptions. A budget is a plan to compare with what actually comes in and goes out, not a promise that every month will match the estimate.
Put the paycheck and bills on one calendar
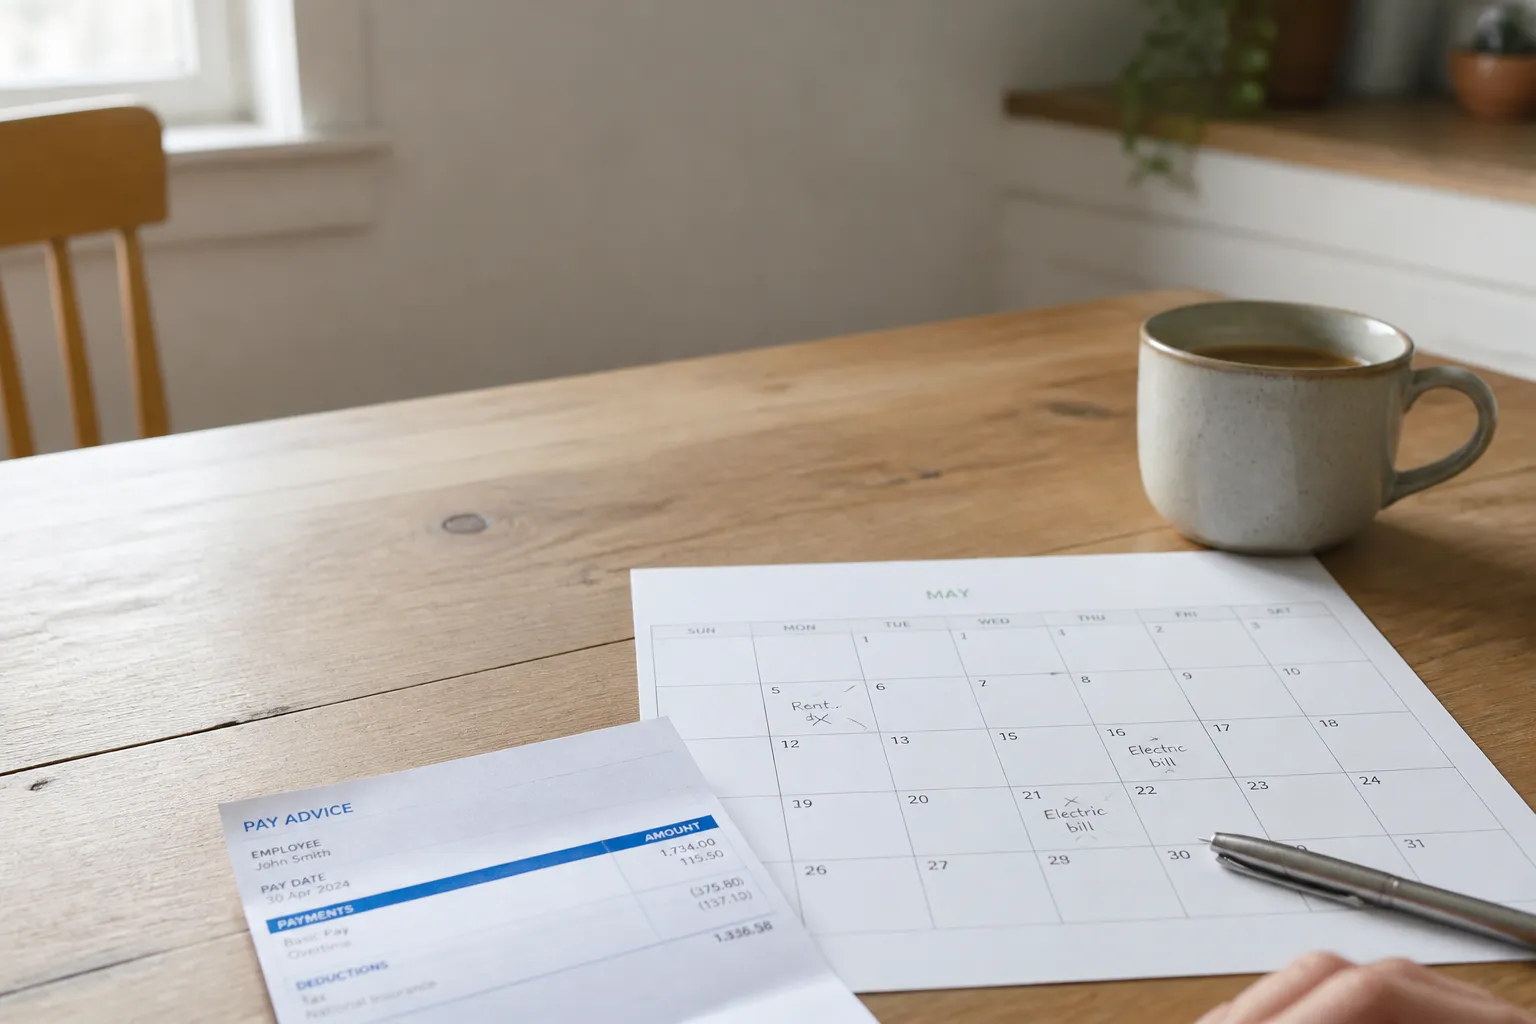
List recurring bills with three details: what each one covers, how much is due, and its due date. Include costs that arrive less often, such as annual or quarterly bills, so they do not surprise the monthly plan. The Consumer Financial Protection Bureau’s bill calendar offers a straightforward way to see what is owed and when.
Mark the new payday on that same calendar. Any bill due before the deposit arrives must be covered by money already available. That timing gap is worth identifying before the first monthly-pay cycle, rather than after a payment is late. If a due date is difficult to manage, you can ask the biller whether a different date is available and confirm when a change would take effect. Do not assume a requested change applies to a payment that is already coming due.
Check the calendar at least weekly. Bills generally keep their due dates even when pay frequency changes, and late payments can bring fees or a negative entry in credit history. A quick review can show whether the next few days include several large expenses, or whether planned spending needs to wait until after a bill is paid.
Give fixed costs first claim on the monthly total
Start the spending plan with expenses that tend to stay about the same: housing, insurance, loan payments, and recurring phone service, for example. Then estimate variable essentials such as groceries, utilities, and transportation. What remains is the amount available for flexible spending and other priorities. This order makes it easier to see a shortfall before the month is underway.
Separate needs from wants as a way to find possible adjustments. The categories are not identical for every household, and a cost can be important even if it is flexible. Still, the distinction can help clarify tradeoffs. If fixed bills and essential costs use most of the monthly income, reducing optional spending may help, but it may not solve a gap that is larger than those choices can cover.
The 50/30/20 rule is one framework for thinking about needs, wants, and saving or debt payoff. Treat those percentages as a guide, not a requirement. Housing costs, income, and other obligations differ, so the useful question is whether the plan covers obligations and leaves an amount that can realistically be assigned to flexible costs and goals. Oregon’s budgeting guidance also recommends estimating fixed expenses as part of making a budget.
Plan for the first cycle, then check what happened
There is no single transition formula that fits every weekly-to-monthly pay change. The first cycle depends on the date of the final weekly deposit, the first monthly deposit, the bills that fall in between, and money already on hand. Write those dates down in order. Then compare the money available on each date with the bills and essential spending due before the next deposit. If the calendar shows a gap, address it early by reviewing expenses and contacting billers about available options.
A monthly deposit can be tempting to treat as spending money for the first few days. Instead, assign portions of it on paper to upcoming bills and the weeks of ordinary expenses ahead. You might divide the remaining amount by the number of weeks until the next payday as a simple way to set a weekly spending pace. That is a planning aid, not a guarantee that every week will cost the same. Irregular expenses and changing needs can still alter the totals.
At month’s end, compare the plan with actual income and spending. Note what arrived, which bills were paid, and where spending differed from the estimate. The Consumer.gov budget worksheet can help organize a monthly review and plan for the next month. Adjust amounts or timing based on what the first cycle showed, rather than assuming the original estimates were exact.
If you can set aside a small cushion, it may help absorb a timing mismatch, but there is no universal cushion amount in the cited budgeting guidance. Build the plan around the money and obligations you actually have. Regular check-ins with a trusted person may also help you notice a calendar problem before it turns into a missed bill.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.