 Credit Score Education
 Credit Reporting & Consumer Rights
 Personal Finance Tips
 Budgeting & Money Management
 Identity Theft & Fraud Prevention
 Credit Card Education
 Consumer Financial News
 Cost of Living & Inflation
 Banking & Savings Education
 Consumer Protection & Financial Literacy

When an institution adjusts the rate paid on a savings account, the monthly document rarely arrives with a banner headline or an alert across the top of the page. Instead, the adjustment surfaces quietly through two accounting figures: the annual percentage yield earned for that cycle and the total dollar amount of interest added to the principal balance.
What a Rate Change Looks Like on the Statement
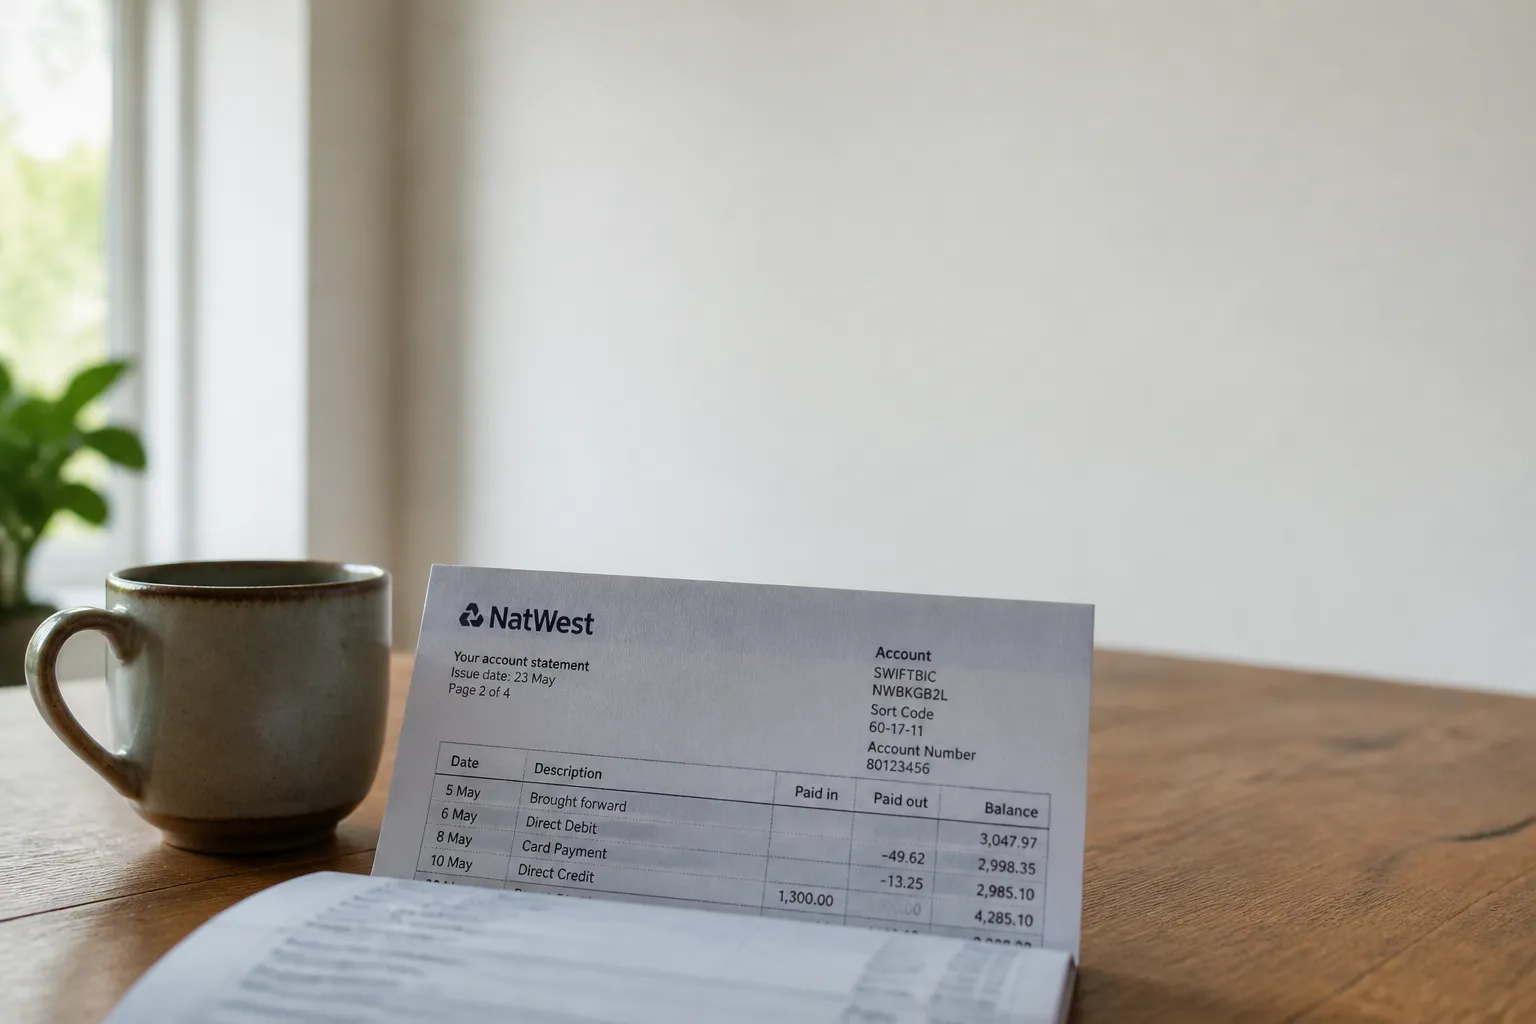
Under federal disclosure standards, a rate revision does not typically appear as an advisory note stating that a rate went up or down. It reflects as a different annual percentage yield, or APY, for the specific statement period, alongside the dollar amount of interest credited during those exact dates. Banks that issue periodic deposit statements must display the APY earned during the cycle at least quarterly, and they are required to use that specific term rather than shorthand alternatives.
Because the yield is calculated and reported for each distinct cycle, laying two consecutive statements side by side provides the clearest record of a change. If the APY listed on one statement is higher or lower than the APY on the previous document, the underlying rate shifted between or within those periods. The dollar figure for interest then reflects the blend of that adjusted rate and the daily balances maintained in the account over the course of the cycle.
The APY functions as a standardized metric. Under Truth in Savings rules, it captures the mathematical effect of compounding over a full annual cycle. The specific calculation framework is detailed in Appendix A to Part 1030 of Regulation DD. While that appendix defines the formal calculation, account holders should not assume a back-of-the-envelope multiplication of their closing balance by the listed yield will match the credited pennies to the digit, as mid-cycle balance shifts and day-count conventions alter the arithmetic.
The Required Content of a Periodic Statement
Depository institutions must observe clear baseline standards whenever they produce periodic paperwork. Under the periodic statement rule established in 12 CFR § 1030.6, a statement must explicitly show the dollar amount of interest earned during the cycle and whether that interest was actually credited to the account. This technical distinction between interest earned and interest credited is critical for recordkeeping. Interest that has accrued remains pending until the institution formally posts it to the ledger, adding it to the withdrawable principal.
Statements must also specify the exact timeframe covered by the accounting. The document must state the total number of days in the period, or list both the beginning and ending dates. These calendar anchors confirm precisely which days were subject to the posted yield, making it possible to trace how long a particular balance earned a given return.
The schedule on which these documents arrive depends on how the account is used. As outlined by the Office of the Comptroller of the Currency's consumer guidance, banks must provide statements at least monthly when electronic fund transfers can occur to or from the account. If no electronic activity takes place, quarterly statements remain mandatory. An account statement arriving less often than these rules require signals an administrative gap worth clarifying with the institution.
How Changes in Terms Are Disclosed
When deposit terms change after an account has already been opened, institutions look to the subsequent disclosure framework. Under 12 CFR § 1030.5, regulatory standards establish how institutions communicate changes in terms to depositors. The provision addresses the baseline obligation to notify account holders when governing terms alter.
Institutions handle interest crediting and computation under distinct procedural rules. Section 1030.7 of Regulation DD governs the legal payment of interest, outlining how balances must be calculated and when earnings must start accruing on deposited funds. The periodic statement rule, the subsequent disclosure rule, and the interest payment rule work in tandem. Together, they dictate what an institution must reveal on periodic documents and how interest calculations must be handled behind the scenes.
Depositors reviewing a rate adjustment can review their initial account agreement alongside the subsequent disclosure rule. The depository institution's initial schedule of terms sets out the conditions under which rates may fluctuate, including whether the rate is fixed or variable, and provides the baseline against which subsequent statement figures must be measured.
Credit Unions and Other Supervisory Frameworks
The rules governing deposit yields extend beyond commercial banks. Credit unions adhere to a parallel statutory framework established by the National Credit Union Administration under NCUA Rules and Regulations Part 707. Across both bank and credit union frameworks, the essential mechanics remain aligned: APY terminology, statement cycle dates, and the explicit reporting of earned earnings remain mandatory components of periodic reports.
Federal regulators monitor compliance with these accounting disclosures through formal supervisory protocols. For example, the FDIC Consumer Compliance Examination Manual details how examiners inspect bank disclosures under Chapter VI-3 to verify that annual percentage yields and crediting entries match regulatory formulas. Federally insured credit unions also operate under federal share insurance, where the National Credit Union Share Insurance Fund covers up to $250,000 per individual account holder across qualifying ownership categories.
While the broader concepts of yield disclosure match across institutional types, presentation designs can differ. Depositors who keep funds at credit unions can consult guidance from the NCUA to review the specific format interpretations applied to share draft and share savings statements.
Questions to Ask When Reading a Statement
When reviewing a periodic savings record, checking three structural items provides a clear picture of how earnings were treated:
- Does the document clearly state the APY earned for that exact cycle, using that precise label?
- Does it state the exact dollar sum of interest earned, and confirm whether those earnings were credited to the balance?
- Does it disclose either the total number of days in the cycle or the calendar start and end dates?
If any of these items are omitted, request a complete periodic summary from the institution in writing. Next, compare the APY earned on the statement against the annual yield described in earlier notices or the original deposit agreement. If the figures show an unexpected drop, ask the institution how the revised rate was established and check their records against the subsequent disclosure guidelines.
Finally, inspect the fee ledger. Regulations require that any administrative fees, maintenance charges, or activity assessments debited during the period be itemized by dollar amount and type. Because fee debits directly reduce principal, an ambiguous fee line makes it difficult to verify whether a change in the ending balance came from an adjusted interest rate or administrative charges. Consumers who believe a disclosure omits mandatory accounting data can contact the Consumer Financial Protection Bureau or the Federal Trade Commission for guidance on consumer deposit protections.
Warning Signs on a Statement
An account summary that completely leaves out the APY earned, skips the dollar value of interest, or fails to define the statement period dates falls short of standard federal disclosure expectations. While formatting can vary widely between printed documents and electronic PDFs, the core metrics must be present. Missing line items make it impossible for a depositor to confirm whether their funds earned the expected yield.
A vague or lumped fee summary is another operational red flag. If maintenance fees or withdrawal deductions are folded into general adjustments without distinct line items, assessing the net return on cash becomes unreliable. Verifying the math requires clear visibility into what entered the account as yield and what left as a service charge.
This overview is educational and focuses strictly on deposit mechanics and statement disclosure rules. It does not address how interest income is taxed, how annual tax forms report aggregate earnings, or legal strategies for deposit management. For inquiries regarding tax liabilities or tax reporting, consult a qualified tax professional.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


