 Credit Score Education
 Credit Reporting & Consumer Rights
 Personal Finance Tips
 Budgeting & Money Management
 Identity Theft & Fraud Prevention
 Credit Card Education
 Consumer Financial News
 Cost of Living & Inflation
 Banking & Savings Education
 Consumer Protection & Financial Literacy

A check is a written instruction directing one financial institution to pay a specified amount of money from an account to another person or business. Before that instruction can be converted into usable cash or deposited into an account, the instrument usually requires an endorsement on the back. When you sign and annotate a check, you provide legal evidence of who transferred the paper and under what conditions the transfer was authorized.
What an endorsement is and why it matters
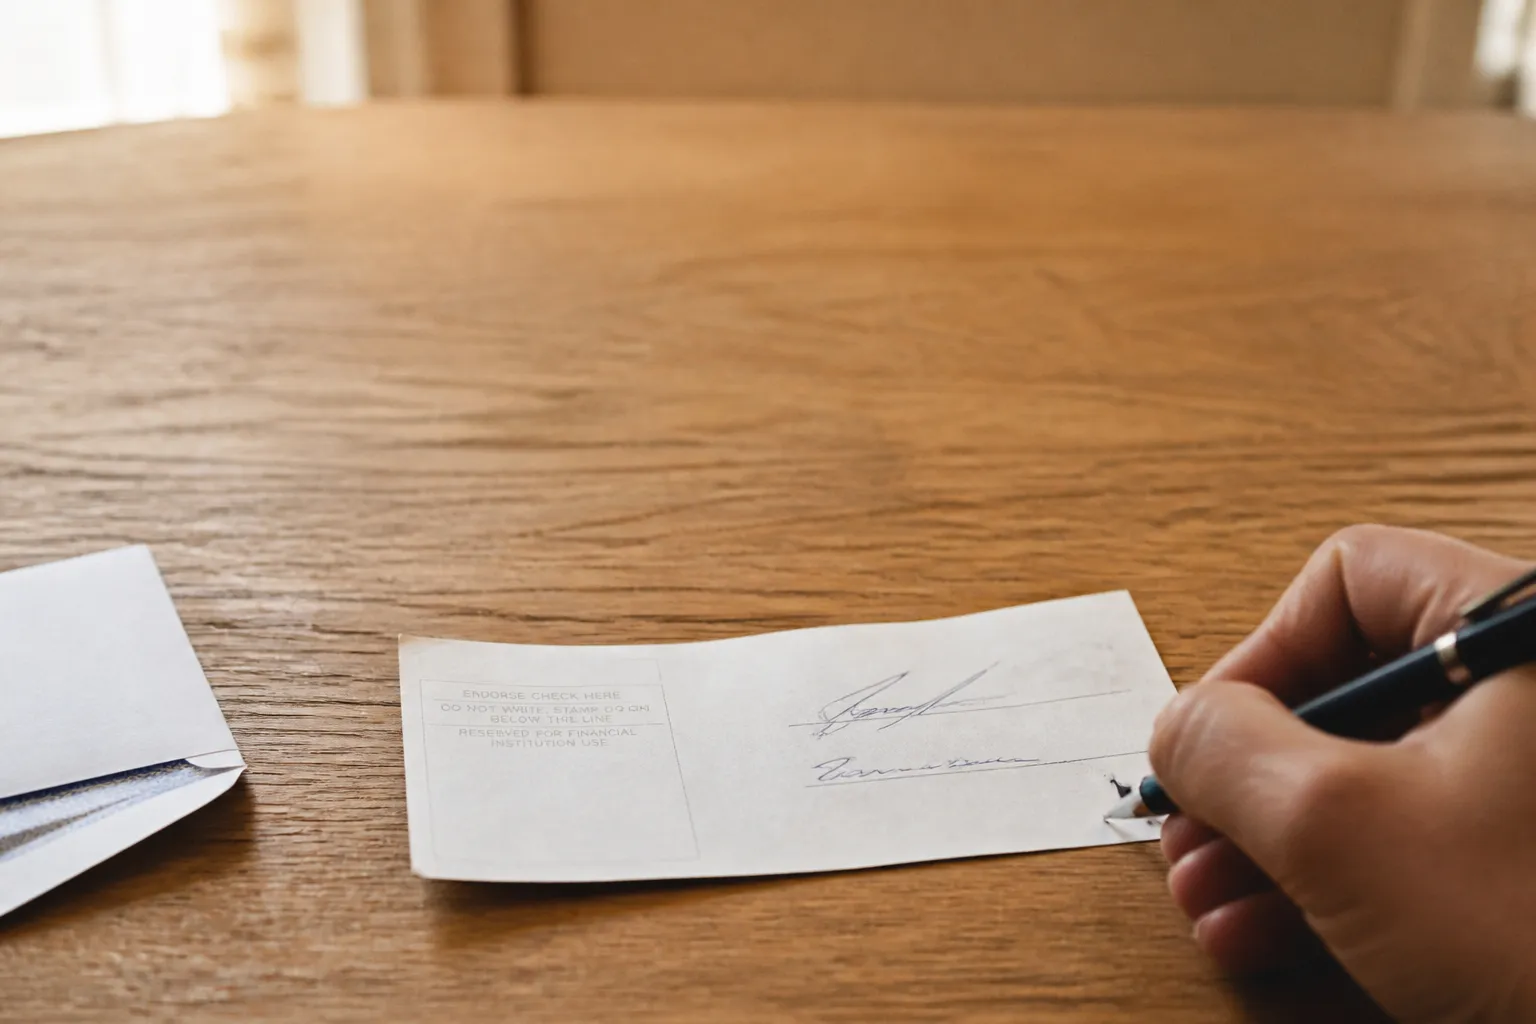
In standard consumer banking, an endorsement consists of the payee writing their signature on the trailing edge of the check's reverse side. For a mobile capture submission, the endorsement serves two related functions. First, it identifies the account holder who presents the item for credit. Second, when paired with specific wording, it creates a restrictive instruction that restricts how the check can be handled. A common mobile deposit instruction requires the payee to sign inside the pre-printed endorsement area and write a restrictive phrase directly below the signature, such as “For Mobile Deposit Only.”
This restrictive line signals that the physical check is already tied to a specific digital deposit transaction. The primary goal of adding this phrasing is to prevent duplicate deposits, where the same check is scanned into a mobile application and later presented as physical paper at a branch counter or automated teller machine. A proper endorsement does not guarantee immediate funds availability, nor does it override an institution's automated duplicate-detection algorithms. Instead, it provides a visible record on the check stock itself, documenting that the instrument was meant solely for electronic image exchange.
How mobile deposit endorsement rules have been shaped by federal regulation
The rules governing check clearing and funds availability are established at the federal level by the Federal Reserve Board through Regulation CC. Effective July 1, 2018, the Federal Reserve amended Regulation CC to address how institutions allocate liability when a check is deposited more than once. Prior to those regulatory changes, liability scenarios often placed the burden on the initial receiving bank if an item was subsequently deposited as a physical check at a second financial institution.
Under the revised framework, the presence or absence of a restrictive endorsement on the physical check plays a pivotal role in duplicate presentment disputes. If a depositor scans a check using mobile deposit without a restrictive endorsement, and that physical check is subsequently cashed or deposited elsewhere, the bank that took the unendorsed mobile deposit may face liability. Because of this risk allocation, financial institutions evaluate their check handling guidelines to reduce exposure. As noted in industry compliance discussions on Regulation CC and mobile deposits, each bank or credit union decides whether to mandate exact restrictive language for consumer accounts.
While federal regulations provide the overarching legal standard, they do not dictate identical wording across all banking applications. One institution may accept a simple restriction, while another mandates its legal institution name written below the signature. Account holders should verify the exact mobile phrasing required by their financial institution before submitting an image.
Which checks and endorsement practices to watch for
Not all negotiable instruments are eligible for remote image capture. Acceptance rules vary according to internal deposit agreements and risk thresholds. Personal checks, business payroll checks, cashier's checks, and United States Treasury checks are commonly permitted through mobile deposit capture. Conversely, institutions frequently reject international checks drawn on foreign institutions, third-party checks, postal money orders, and traveler's checks through digital channels.
Depositors must exercise particular care with certain types of instruments and handling habits, as outlined in guides on how to endorse a check for mobile deposit:
- Third-party checks: A check made out to one party and signed over to someone else carries higher risk of forgery or return, causing many banks to prohibit remote deposit entirely.
- Checks payable to multiple payees: When a check is issued to two individuals joined by “and,” both signatures are generally required. If joined by “or,” rules can vary, and remote capture systems may require branch verification.
- Premature signatures: Signing a check long before you are ready to complete the transaction creates substantial risk. A check signed with a bare signature becomes bearer paper, meaning anyone who gains possession of the physical paper may attempt to negotiate it.
- Checks from unfamiliar sources: You should never deposit an instrument received from an unknown sender or tied to unexpected instructions, as returned check fees and reversal of provisional credits can follow.
The legal background: blank, special, and anomalous endorsements
The statutory mechanics governing check transfers originate in state adoptions of the Uniform Commercial Code (UCC). Under UCC Section 3-205, the law distinguishes among several key categories of endorsements that govern how an instrument may be negotiated.
A blank indorsement occurs when the payee simply writes their signature without specifying an endorsee. By operation of law, a blank indorsement converts the order paper into bearer paper. While in bearer form, the check may be negotiated by transfer of possession alone until it is specially indorsed. However, the UCC allows a holder to convert a blank indorsement into a special indorsement by writing, above the signature, words that direct payment to a specific individual or entity.
A special indorsement names a specific person or entity to whom the instrument is made payable. Once specially indorsed, the check requires that designated person's signature for any further valid negotiation. The statute also identifies an anomalous indorsement, which is an endorsement placed on an instrument by a party who is not the holder. Under the UCC, an anomalous indorsement acts as an accommodation or guarantee but does not affect the manner in which the underlying instrument is transferred.
Additional rules covering restrictive conditions are codified in UCC Section 3-206. While commercial code provisions provide the underlying legal architecture, they operate alongside federal banking rules and private deposit account agreements that define account rules.
Questions to ask your bank and remaining gaps
Before submitting an item via mobile capture or presenting it at a branch counter, depositors should confirm specific requirements directly with their institution. Clarifying operational details ahead of time reduces the risk of rejected scans or unexpected holds. Useful questions to raise include:
- What specific phrasing must appear under the signature on the back of the check for mobile deposit?
- Does the institution permit mobile submission of cashier's checks, government checks, or items with two named payees?
- How does the institution handle physical retention and disposal of the paper check once a digital deposit is confirmed?
Federal deposit oversight operates across distinct regulatory agencies. For instance, the National Credit Union Administration oversees the application of the Expedited Funds Availability Act under NCUA deposit regulations, while administering share insurance coverage up to $250,000 per qualifying account. General federal compliance standards for banks are outlined through FDIC consumer deposit guidelines. Depositors should remember that federal deposit insurance covers financial institution insolvency, not check settlement losses or check fraud liabilities.
Statutory materials and basic guides leave several practical questions to individual bank policy. They do not set universal timelines for funds availability holds on mobile deposits, nor do they detail the specific steps required if an automated image capture algorithm rejects a faint endorsement. For unresolved check disputes or concerns regarding improper deposit handling, consumers can seek guidance or lodge inquiries through official regulatory channels such as the Consumer Financial Protection Bureau or the Federal Trade Commission.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


