 Credit Score Education
 Credit Reporting & Consumer Rights
 Personal Finance Tips
 Budgeting & Money Management
 Identity Theft & Fraud Prevention
 Credit Card Education
 Consumer Financial News
 Cost of Living & Inflation
 Banking & Savings Education
 Consumer Protection & Financial Literacy

A credit counseling session can feel easier when you arrive with a few numbers, a copy of your credit report if you have one, and questions written down. You do not need a perfect budget or a complete file of paperwork. A clear picture of what comes in, what goes out, and what you owe gives the counselor a useful starting point.
Know what a nonprofit credit counselor can do
Credit counseling organizations are usually nonprofits, and their counselors are typically trained in consumer credit, budgeting, and money and debt management. A counselor can review your finances, help you build a budget, explain options, and help you obtain copies of your credit report and scores. Some organizations also offer educational materials and workshops. The CFPB’s overview of credit counseling is a useful starting point for understanding the service.
A counselor may discuss a debt management plan, but that is only one possible route. A plan can organize payments to creditors, and counselors may try to negotiate terms such as lower interest rates or fees. It does not erase what you owe. Ask which debts could be included, what the plan would require, and what alternatives the counselor sees. A counselor is not a substitute for a lawyer or tax professional, so ask the appropriate professional about legal or tax questions.
Sessions are commonly offered in person, online, or by phone. Choose a format that lets you speak comfortably and refer to your notes. An initial session often lasts about an hour, with follow-up sessions available. The Financial Counseling Association of America’s preparation guidance describes what a counselor may review. FCAA is an industry association, not a government regulator, so consider it one source of information.
Bring a workable snapshot of your finances
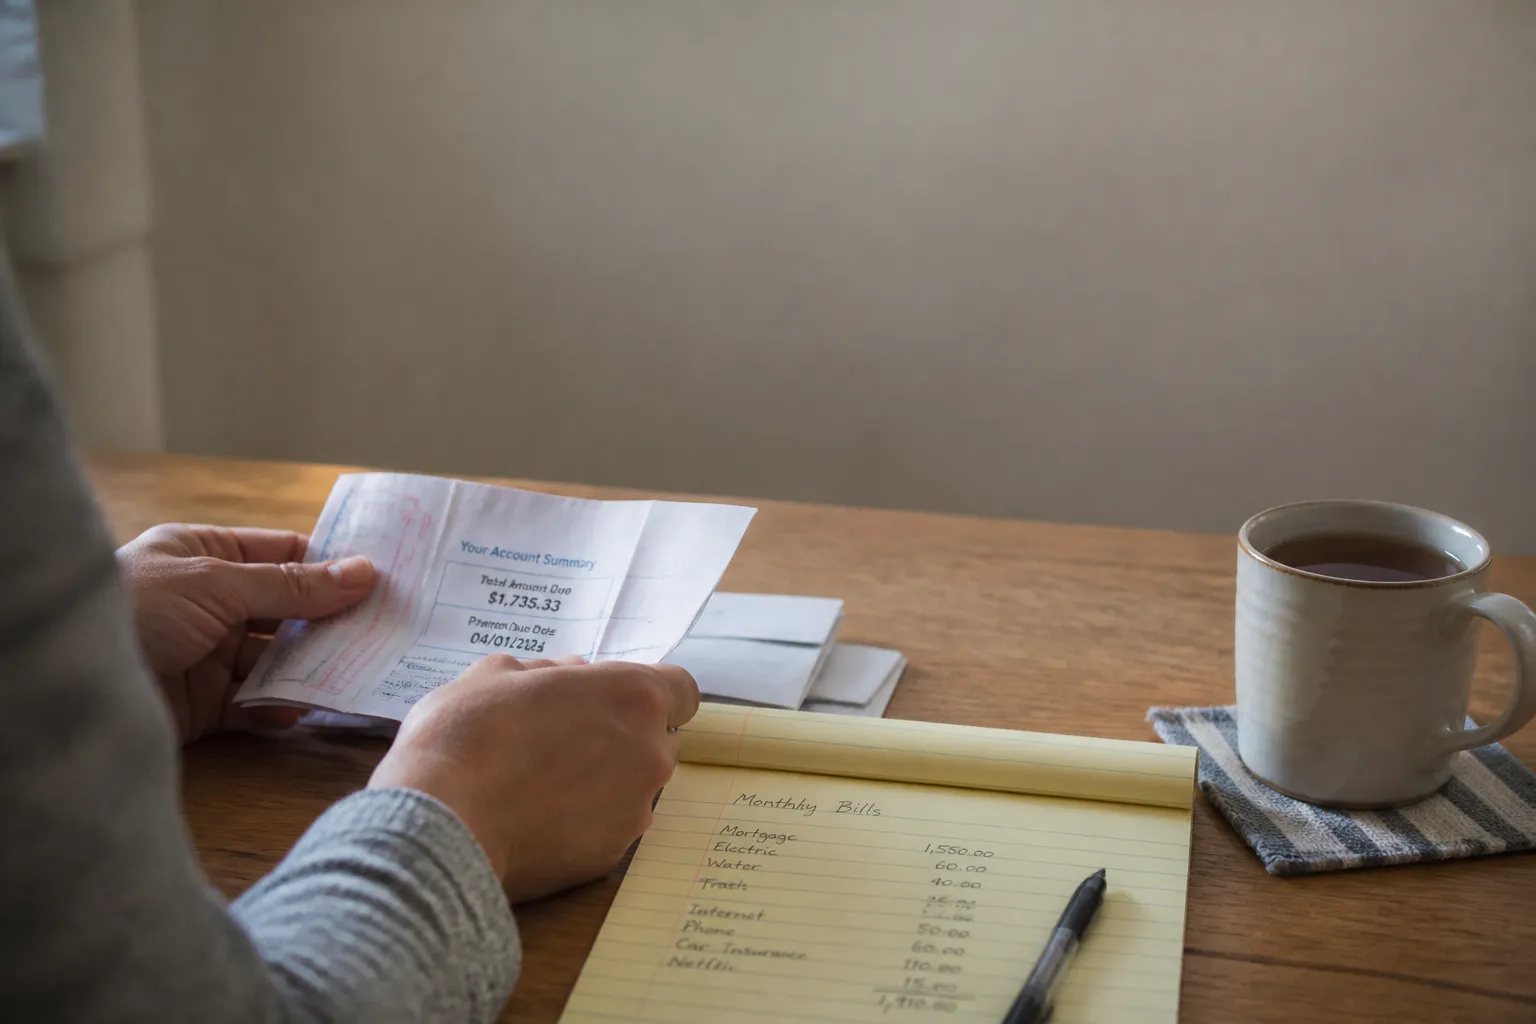
Before the appointment, gather what you can about your income, expenses, assets, and debts. A recent pay stub can help you estimate take-home pay. If your income varies, note that and use a time period that gives a realistic picture. For expenses, jot down recurring costs such as housing, utilities, food, transportation, insurance, and minimum payments. Estimates are useful when exact totals are not handy.
For each debt, write down the company or creditor, approximate balance, interest rate if known, and minimum monthly payment. Include accounts that are past due or in collections. If you are unsure about a number, mark it as an estimate instead of delaying the session to track it down. You can also note assets or savings if you are comfortable sharing that information with the counselor.
If you have a credit report, bring a copy or make notes about items you want to ask about. Look for accounts you do not recognize, balances that seem inaccurate, and payment history you believe may be wrong. The sources here do not provide step-by-step instructions for getting a report or disputing an error. For those details, use the CFPB’s credit counseling information and consult official consumer resources. Keep your notes factual, such as “I do not recognize this account,” rather than guessing at the cause.
Write down your goal in one or two sentences. You might want to understand your options, make a monthly budget, or find out whether a repayment plan could fit your circumstances. A specific goal gives the conversation a direction without requiring you to decide in advance what solution you will choose.
Check the organization, its qualifications, and its fees
Ask whether the organization is a nonprofit and whether it has recognized accreditation. Confirm the counselor’s training or certification in consumer credit. Affiliation with an industry association may offer one useful clue, but it is not a government endorsement or a guarantee of results. If bankruptcy is part of what you are considering, the U.S. Trustee Program publishes a list of approved credit counseling agencies. The program says it does not recommend a particular agency or guarantee an outcome. Its credit counseling FAQ explains the bankruptcy-related requirement and list.
Ask about cost before sharing detailed financial information or agreeing to a service. Credit counseling organizations are allowed to charge fees. Some offer an initial session at no cost, while a debt management plan may have ongoing fees. One source gives a general monthly range of about $25 to $50 for maintaining a plan, but costs and services can vary. Treat that figure as a prompt to ask, not as a quote. Request a written fee schedule, including any setup or monthly charges, and ask what basic information or services are free.
The FTC’s guide to choosing a credit counselor suggests asking what services are offered, whether information is free, what the fees are, what qualifications the counselor has, how confidential your information will be, and how long a debt management plan may take. You can bring these questions on paper and take notes on the answers.
Ask direct questions and watch for pressure
Before you enroll in anything, ask how the organization handles your personal information and whether it will share it. Counseling sessions are generally confidential, and counselors do not report to credit bureaus, but ask for the policy in writing so you understand the limits. Also ask whether a plan would cover every debt you have, what happens if your circumstances change, and what your responsibilities would be each month.
Pay attention to how the counselor explains your options. A careful explanation should make room for questions and should not make a debt management plan sound like the only choice. Be cautious if an organization asks for payment before providing services, pushes you to sign up quickly, promises to dramatically reduce your debt, or asks for detailed financial information before clearly identifying itself and explaining its services.
Also distinguish credit counseling from debt settlement or other debt relief services. The CFPB’s comparison of credit counseling and debt relief options notes that for-profit debt relief companies may charge high fees and may advise people to stop paying creditors. That can have serious consequences, including harm to credit. Ask the organization to explain plainly what kind of service it provides and how it is paid.
Leave with written next steps, not a rushed decision
During a first session, the counselor may review your income, expenses, assets, debts, and goals, then discuss possible next steps. If you consider a debt management plan, ask for the proposed payment, fees, estimated timeline, and the terms that would apply to your accounts in writing. A plan generally involves sending one monthly payment to the counseling organization, which then pays creditors. Counselors may seek changes such as a longer repayment period, reduced interest, or waived fees, but those changes are not guaranteed.
Ask what happens if you miss a payment or need to leave the plan. The available sources do not explain every plan’s rules or how a debt management plan may affect a credit score, so get answers specific to the written terms before deciding. The CFPB says these arrangements usually do not affect taxes, but tax treatment can vary. A tax professional can address questions about your situation.
After the session, review any written materials at your own pace. Compare the proposed costs and commitments with the options discussed, and contact official resources such as the CFPB or the FTC if you need more consumer guidance. Taking organized notes into the appointment can help you use the hour well, and you can ask for time to think before agreeing to a plan.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


