 Credit Score Education
 Credit Reporting & Consumer Rights
 Personal Finance Tips
 Budgeting & Money Management
 Identity Theft & Fraud Prevention
 Credit Card Education
 Consumer Financial News
 Cost of Living & Inflation
 Banking & Savings Education
 Consumer Protection & Financial Literacy

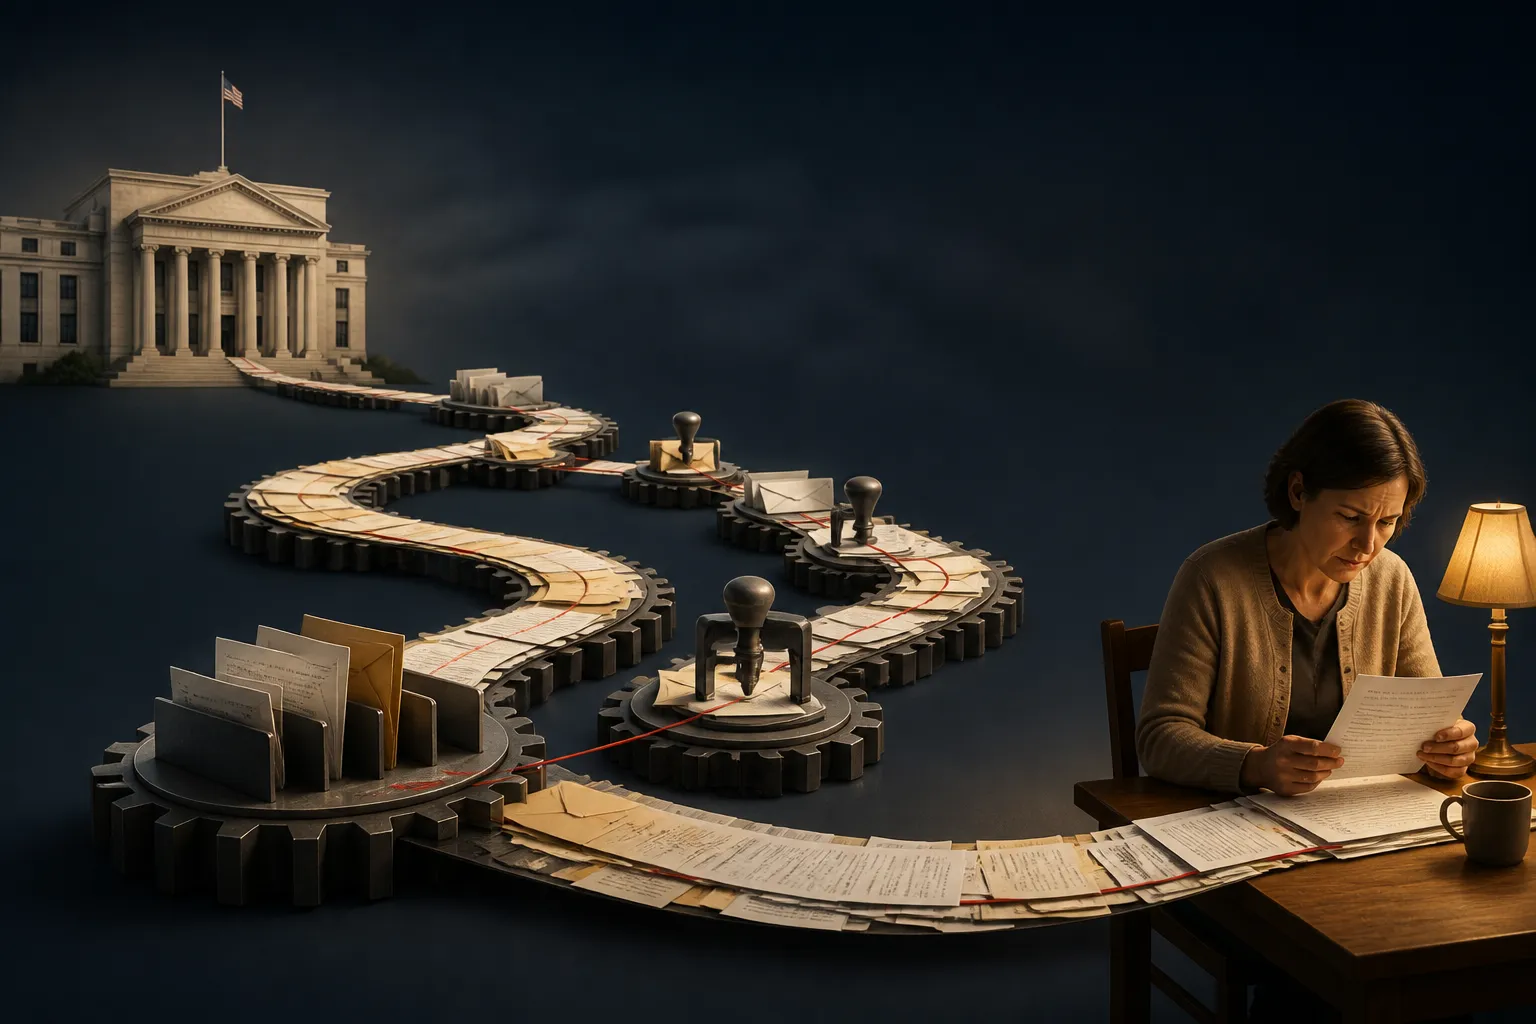
A policy change in Washington does not arrive at your mailbox as a policy change. It arrives as a notice, a new number on a statement, or a bigger autopay withdrawal you did not expect. Somewhere between the Department of Education's announcement and your account, a chain of contracts and deadlines decides what you actually experience, and that chain has more weak links than most borrowers assume.
Who sits between the rule and the borrower
The Department of Education writes the rules for federal student loan programs, covering a portfolio of roughly $1.6 trillion. It does not, as a rule, send your bill or pick up the phone when you call with a question. That job belongs to loan servicers, the companies Education contracts with to handle billing, account processing, and borrower communication. When a program changes, Education has to translate the change into instructions, and the servicer has to translate those instructions into letters, account updates, and new payment amounts.
- Education defines a policy or program change at the federal level.
- The agency sends implementation instructions to its contracted servicers.
- Servicers update account systems and issue notices, which is the version of the change a borrower actually sees.
Each step in that sequence takes time, and each one is a place where wording, timing, or math can drift from the original announcement. A federal government oversight review looked at exactly this handoff and found it is not as tight as borrowers might hope.
- Several servicers reported a lack of clear up-front instruction from Education, which in some cases led to extended back-and-forth before work could even start.
- One servicer said it had just one business day to update how it tracked borrowers' progress toward loan forgiveness, leaving little time to test the change before it touched real accounts.
- Oversight reviewers found that most of the five contracted servicers lacked the kind of coordination arrangements Education itself needs to catch problems early.
Where implementation breaks down
None of this is abstract to a borrower checking a statement. When instructions are rushed or unclear, the downstream effect is a servicer scrambling to catch up, and sometimes getting it wrong. Billing information can be inaccurate for weeks or months while the error gets traced back to its source. If your statement does not match what you were told on the phone or in writing, that mismatch is worth treating as a possible processing issue on the servicer's end, not evidence that you misunderstood your own loan.
The SAVE plan timeline as a case study
The SAVE repayment plan is a useful, if frustrating, illustration of how this plays out in real time. A federal court order issued March 10, 2026 blocked Education from implementing SAVE, which set off a wave of servicer action. Servicers began sending SAVE exit notices around July 1, 2026, each one starting a 90-day window for the borrower to pick a different repayment plan. Some borrowers who got that first notice later received a final 30-day notice as well, and as of this writing Education had not publicly announced any extension of the 90-day period.
Borrowers who do not choose a new plan within their servicer's window are not left without one. They are automatically moved into either the Standard plan or a newer Tiered Standard plan that became available July 1, 2026, with the choice depending on when the loans were made or entered repayment. Both are fixed payment plans. That matters because a fixed payment can land well above what an income-driven plan required, so doing nothing is itself a decision with a dollar amount attached.
What borrowers should check and when
Servicers are required to notify borrowers of a new monthly payment at least 21 days before the first due date tied to that payment. That notice, not the general news coverage of a policy change, is the document that matters for planning. Anyone on autopay should treat a plan change as a trigger to double-check the withdrawal amount and date, since the automatic payment rises along with the new bill without necessarily sending a separate warning.
- Ask the servicer what the specific 90-day deadline is for your account, and whether a final notice has already gone out.
- Ask what your new monthly payment will be and whether your autopay amount is changing with it.
- Write down the date of the call, the representative's name, and the answers given, in case the account later shows something different.
Borrowers are not required to wait for a deadline to act. You can contact your servicer at any time to enroll in a different plan, and doing so before the servicer's own cutoff date, rather than a general public deadline, is what keeps the account on the borrower's preferred terms instead of a default one.
Warning signs and open questions
Mismatched billing figures after any program change are one of the clearer signs that something slipped in the handoff between Education and a servicer, rather than a sign that the borrower did something wrong. It is worth documenting in writing and raising promptly so there is a paper trail if it needs to be corrected later.
There are also real gaps in what is publicly known right now. The available record does not explain how a borrower can verify that a notice from a servicer is legitimate, or what formal channel exists to report a billing error. It is not clear whether the 90-day SAVE window will be extended, what the exact payment terms of the Tiered Standard plan look like, or how servicer oversight recommendations from federal reviewers will be enforced going forward. For current answers on any of these points, the Federal Student Aid website, the Department of Education, and the Consumer Financial Protection Bureau are the places to check before making a decision about your account.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


