 Credit Score Education
 Credit Reporting & Consumer Rights
 Personal Finance Tips
 Budgeting & Money Management
 Identity Theft & Fraud Prevention
 Credit Card Education
 Consumer Financial News
 Cost of Living & Inflation
 Banking & Savings Education
 Consumer Protection & Financial Literacy

Mortgage underwriting places heavy weight on credit reports and credit scores, where even a slight reporting discrepancy can change the pricing or approval terms of a home loan. When a borrower pays off a balance, removes an erroneous charge, or discovers an inaccurate late payment during the underwriting window, timing becomes a critical issue.
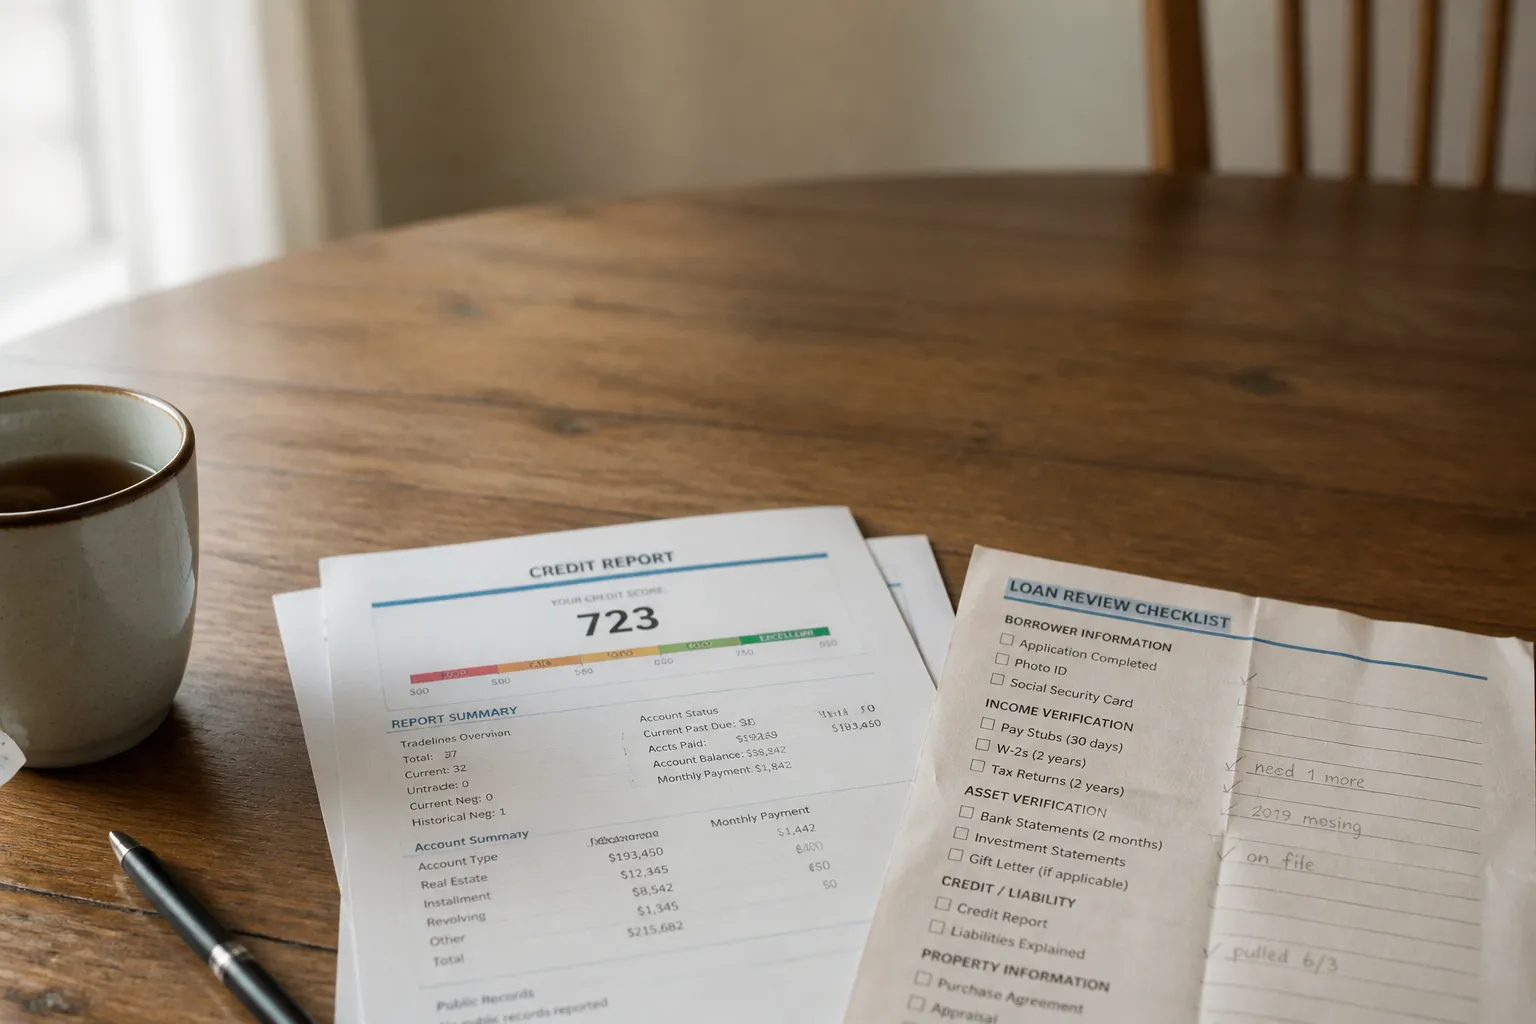
Borrowers often seek out options to reflect those recent changes immediately rather than waiting for normal thirty-day bureau reporting cycles. This pressure leads many applicants to ask their loan officers about rapid rescoring to refresh their credit scores before closing.
While rapid rescoring is commonly discussed among industry professionals, the official secondary market standards that govern conventional mortgages describe credit evaluation in much more conservative, procedural terms.
What the Available Guidance Covers
Fannie Mae publishes rules for lenders in its Selling Guide. This document is written for financial institutions that originate loans for Fannie Mae to purchase or securitize, rather than for the general public. Within this framework, two key sections address how credit files and scores must be handled during underwriting.
According to Fannie Mae's standard on the accuracy of credit information in a credit report, the lender holds the ultimate duty to review all credit information. This requirement applies to all mortgage loans, whether they are manually underwritten by a human analyst or evaluated through an automated system such as Desktop Underwriter (DU). For consumers, the central takeaway is that an automated underwriting finding does not relieve a lender of its obligation to review the underlying report for accuracy and consistency.
A separate standard outlines Fannie Mae's general requirements for credit scores. This guidance establishes that credit scores are required for most conventional loans that Fannie Mae buys or backs. The page outlines several core topics, including which credit score versions apply, minimum score thresholds, exceptions to those minimums, DU-specific scoring rules, score delivery protocols, and loan-level price adjustments tied to borrower credit scores. However, the available public excerpts stop before listing the exact numeric minimums, specific exception criteria, or price adjustment tables, meaning those specific thresholds cannot be assumed without complete documentation.
What Rapid Rescoring Is, and What the Sources Do Not Say
In retail mortgage lending, rapid rescoring typically refers to an expedited process where a lender asks a credit reporting vendor to update tradelines using recent documentation, such as a payoff letter or a zero-balance receipt. Despite its frequent mention in mortgage marketing and consumer forums, the reviewed Fannie Mae guidance does not define rapid rescoring, describe its technical mechanics, or state who has permission to request it.
The official pages also omit operational details such as turnaround times and fees. They do not state whether a rescore takes two business days or two weeks, nor do they specify whether a borrower or a lender absorbs the associated processing costs. In practice, operational procedures and permitted fees depend on individual lender policies, credit repository agreements, and federal fee regulations. Borrowers asking about rapid updates must obtain those specific terms from their loan officer in writing.
Because regulatory and agency excerpts are often condensed, readers should avoid drawing broad conclusions about what secondary market investors permit. An underwriter may have access to specific vendor tools to clear up an error, but the procedural rules governing those tools require a full, unedited reading of primary agency source materials.
Disputed Accounts and the Borrower's Role
Fannie Mae's credit accuracy guidance explicitly includes a distinct subsection dedicated to disputed tradelines. A disputed tradeline is an individual account on a credit report that a borrower has formally challenged as incorrect or fraudulent. While the guidance confirms that underwriters must apply specific rules to these accounts, the reviewed text does not provide the exact procedural steps lenders must take or what evidence a borrower must supply to clear the dispute.
Outside of secondary mortgage guidance, general federal consumer protection rules define how disputes operate. Under the Fair Credit Reporting Act, consumers have the legal right to challenge inaccurate, incomplete, or unverifiable information directly with consumer reporting agencies and with the creditors that furnished the data. Agencies like the Consumer Financial Protection Bureau (CFPB) and the Federal Trade Commission (FTC) maintain consumer education materials explaining how to submit disputes and what timelines furnishers must follow when investigating claims.
When an active dispute appears on a credit report during mortgage underwriting, automated systems may issue warnings or require manual review. A borrower navigating a home purchase or refinance should take clear, methodical steps to protect their application:
- Maintain detailed written records of all dispute correspondence, including certified mail receipts, confirmation numbers, and creditor responses.
- Disclose any open or recent disputes to the mortgage loan officer as early in the application process as possible.
- Request clear guidance from the lender on whether open dispute notations must be resolved or removed before final loan approval.
Where to Find Firmer Consumer Information
Fannie Mae's Selling Guide serves a specific purpose: establishing terms between loan originators and the secondary market. It does not govern government-insured loan programs like the Federal Housing Administration (FHA), the Department of Veterans Affairs (VA), or the United States Department of Agriculture (USDA), nor does it apply to private portfolio lenders or Freddie Mac.
Consumers seeking reliable, non-commercial information about credit reports should consult official federal authorities. The CFPB and FTC provide guides detailing statutory consumer rights, dispute templates, and explanations of how credit scores work. Additionally, federal law entitles consumers to free copies of their credit reports from Equifax, Experian, and TransUnion through the federally authorized portal, AnnualCreditReport.com. Checking these reports well before submitting a mortgage application allows borrowers to spot and dispute inaccuracies without the time pressure of an impending closing date.
Because credit policies vary widely across institutions, consumers should request their lender's written policies on credit score updates, dispute handling, and manual underwrites. For independent, personalized guidance, consumers can also consult a housing counselor approved by the U.S. Department of Housing and Urban Development (HUD). This article provides educational information on underwriting standards and does not constitute individual legal, tax, or financial advice.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


