 Credit Score Education
 Credit Reporting & Consumer Rights
 Personal Finance Tips
 Budgeting & Money Management
 Identity Theft & Fraud Prevention
 Credit Card Education
 Consumer Financial News
 Cost of Living & Inflation
 Banking & Savings Education
 Consumer Protection & Financial Literacy

Your first year after college brings a new rhythm of paydays, rent, utilities, and debt payments. Campus life used to absorb some of those costs. A budget makes the pattern visible before a bill is due. Start with the dates and amounts you can verify, then revise as real spending comes in.
Start with the planning tools that exist
The Consumer Financial Protection Bureau (CFPB) publishes three resources for people learning to plan: a worksheet on planning a financial path after graduation, a budget scenarios handout, and a guide to learning about budgets. The titles suggest hands-on activities rather than a single set of rules.
We could confirm the titles but not what the worksheets ask you to record. Open each one yourself. While you do, grab a blank calendar and your own bills and start filling in the month.
Put paydays and bills on one calendar
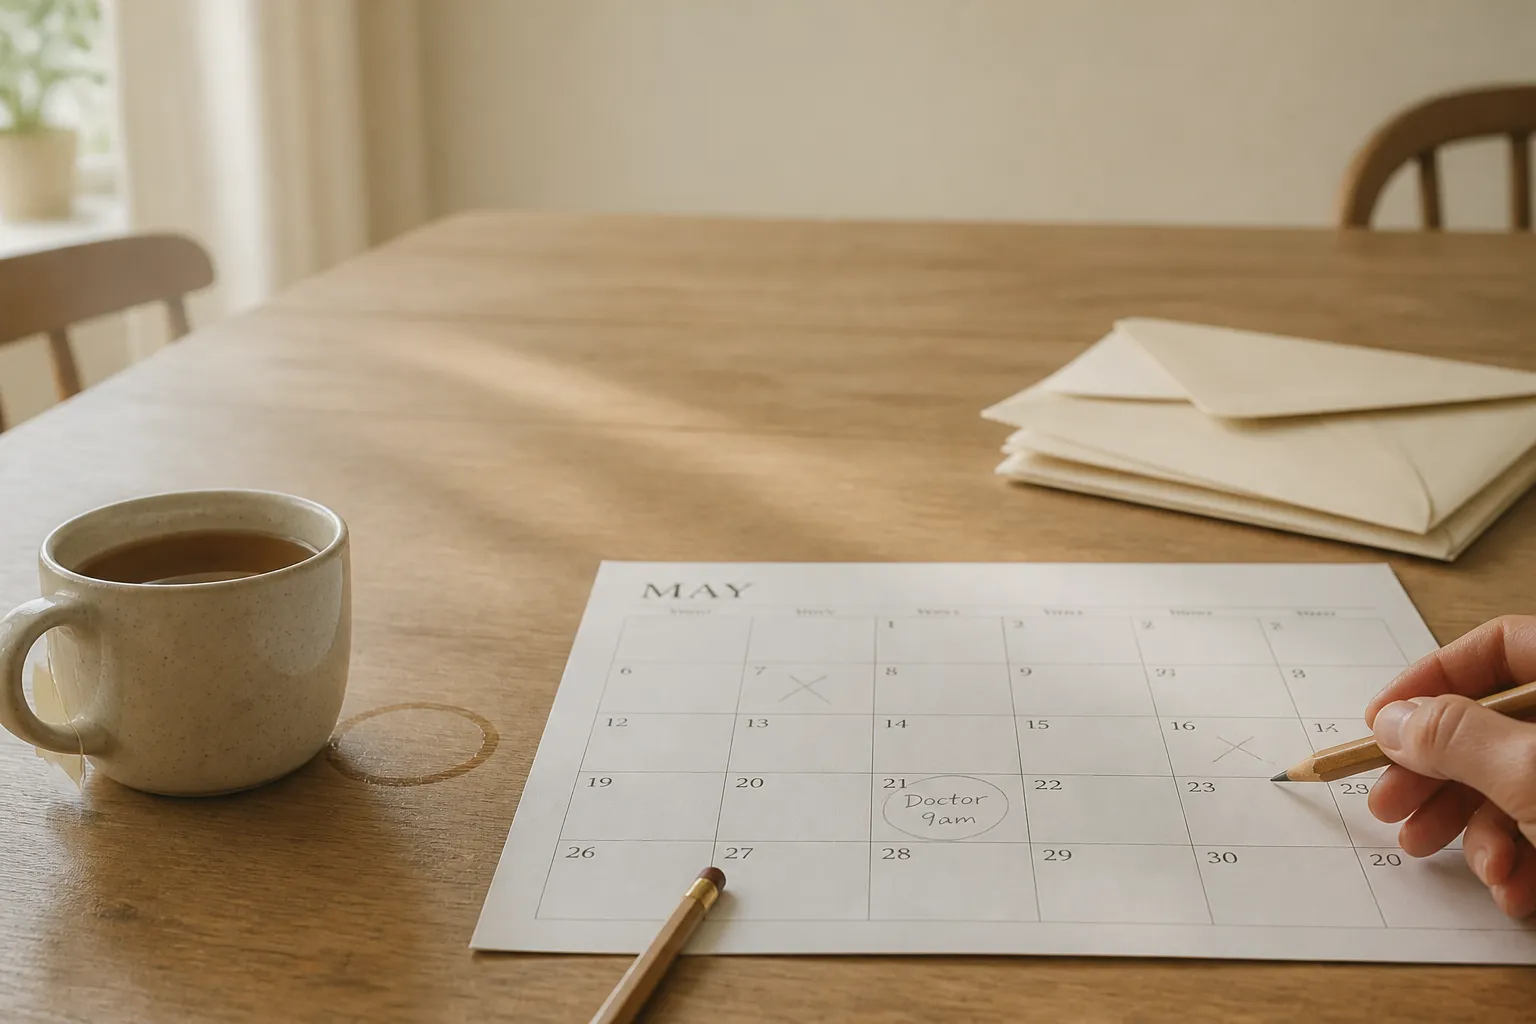
Write down each expected payday and each bill's due date. Include rent, utilities, transportation, insurance, and debt payments. Use amounts from current statements, contracts, or account records. Mark anything that changes monthly as an estimate, and check it against actual spending later.
Here is an illustration with made-up numbers. Say your first paycheck of $1,800 lands on the 15th. Rent of $950 is due on the 1st, and a $60 phone bill is due on the 5th. Those bills come due before any money arrives. The monthly total may look fine, yet the first two weeks are short. The calendar shows that at a glance.
When a bill lands before payday, call the biller. Some will move the due date or tell you what happens if a payment is a few days late. Ask before the date passes, not after. Policies differ, so get the answer in writing if you can.
Turn the calendar into a spending plan
Begin with take-home pay, the amount that actually reaches your account after payroll deductions. If your hours vary, use a cautious estimate. Do not count a possible bonus, extra shift, or reimbursement as money you already have.
Then sort expenses by how predictable they are. Rent is committed. Groceries can flex. An occasional repair is a guess. You do not need a perfect system. You need to know which numbers are firm and which are not.
Subtract what you have recorded and look at what remains. Costs that are easy to forget, like household supplies or transit, can eat that margin. Adjust your estimates before you call the remainder free to spend. Keep a short note of your assumptions. A new job, a move, or a change in benefits can make last month's plan out of date.
Skip the universal split
None of the sources we reviewed give budget percentages, dollar targets, or rent guidance. Two graduates with the same take-home pay can face very different rent, commutes, and family obligations. A percentage from a general article may fit neither of them.
When the first draft does not balance, look at what can move. A lease is hard to change mid-year. A grocery budget is easier. Write down each tradeoff with its timing: what would change, how soon it would help, and what might take its place.
If money is left after bills and everyday costs, you decide how to divide it among near-term savings, debt payments, and other goals. A CNBC Select article, which carries affiliate links, attributes advice to a financial planner to build credit, build an emergency fund, and pay yourself first. We could not see how it explains any of those, so treat them as topics to research, not instructions.
Review the plan at month's end
Compare the draft with what happened. Note bills that differed from the estimate, surprise expenses, and dates that were awkward. Then fix next month's calendar. The first version will be wrong in places. That is useful, because it gives you specific numbers to correct.
For federal student loan terms and repayment, use official Federal Student Aid resources and your loan servicer. The CFP Board's Let's Make a Plan site also has a grad guide and an adulting checklist, though we could not read their full text. Check them directly before relying on them.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


