 Credit Score Education
 Credit Reporting & Consumer Rights
 Personal Finance Tips
 Budgeting & Money Management
 Identity Theft & Fraud Prevention
 Credit Card Education
 Consumer Financial News
 Cost of Living & Inflation
 Banking & Savings Education
 Consumer Protection & Financial Literacy

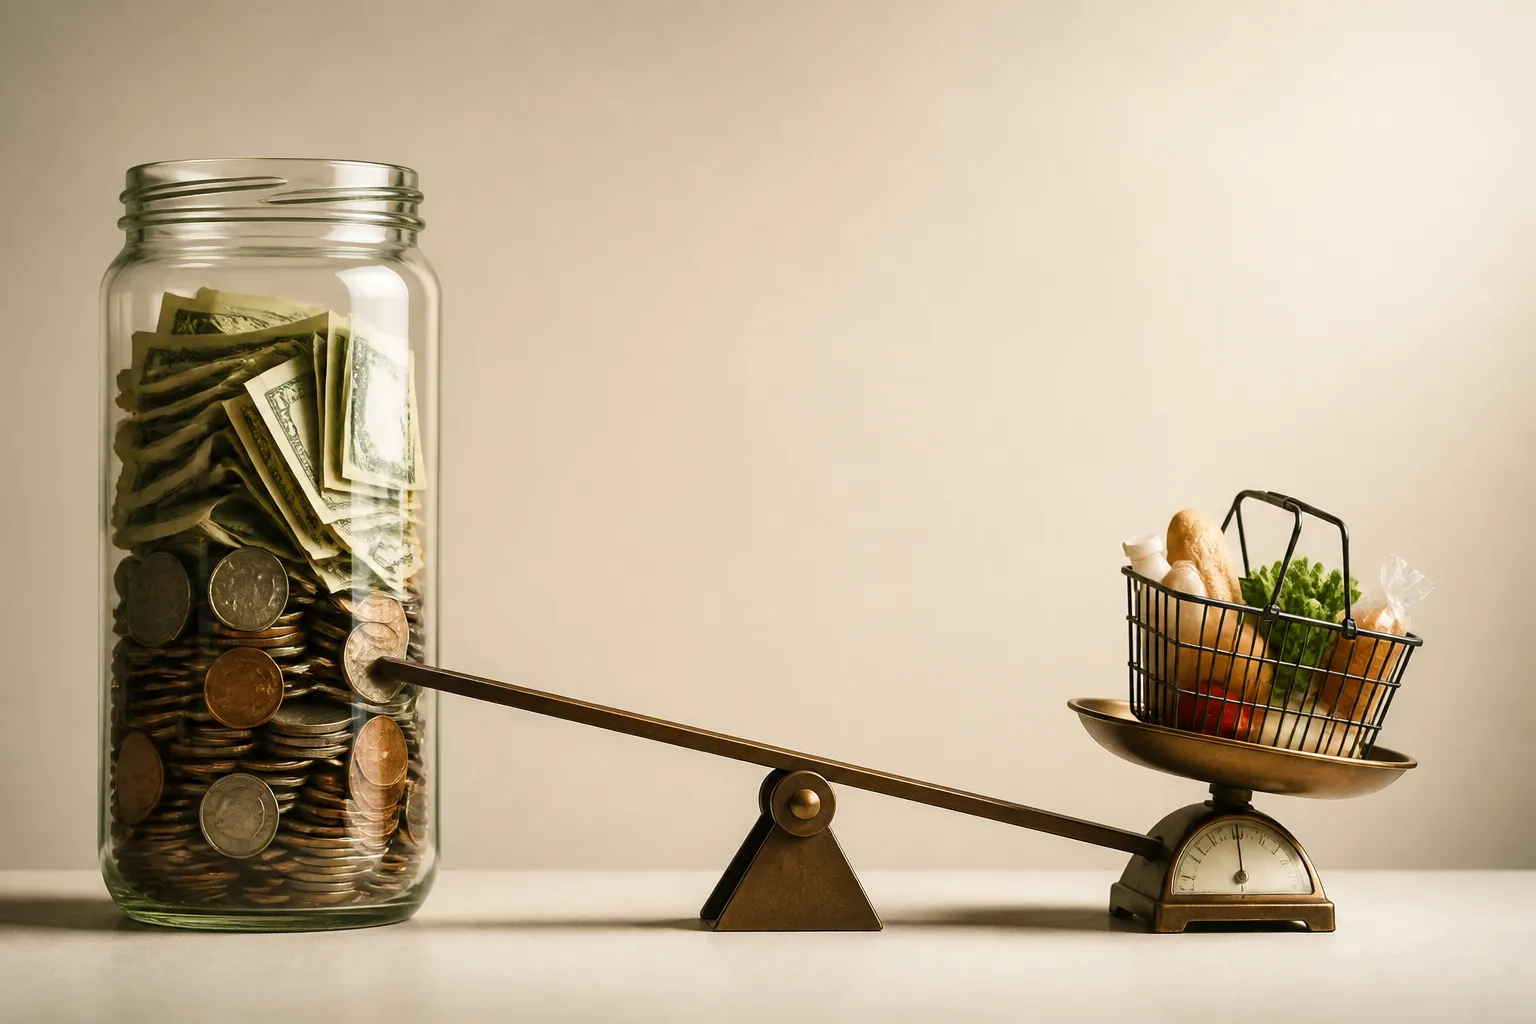
A bank statement can show a balance that ticks upward every month, yet still leaves a household with less buying power than when the money was first set aside. That discrepancy between the numbers on a screen and the goods those dollars actually purchase is the core mechanism of inflation. When prices across the economy climb faster than an account earns interest, cash loses ground quietly.
What inflation actually measures
Inflation is defined as a general, sustained upward movement in the prices of goods and services across an entire economy. It is not simply a spike in the cost of a single household item, such as a carton of eggs or a gallon of gasoline. Price swings for isolated items happen constantly due to local supply bottlenecks, weather disruptions, or seasonal demand. Inflation, by contrast, refers to a broader trend where many prices rise together, reducing the purchasing power of the currency over time.
Purchasing power reflects the actual volume of groceries, utilities, housing, and clothing that a single dollar commands. When broad inflation sets in, each dollar buys a smaller basket of those everyday items. Maintaining price stability is one of the statutory responsibilities assigned to the Federal Reserve System. For readers interested in how policymakers assess these macroeconomic trends, the central bank provides background on its public portal about how it evaluates changes in the rate of inflation.
To measure these price changes over time, public agencies track large surveys of consumer spending. The Bureau of Labor Statistics publishes the Consumer Price Index, which tracks what typical urban households pay for a defined collection of goods and services. A detailed look at how earnings and price indexes interact is detailed in the agency's publication on income and the Consumer Price Index. That index serves as a nationwide benchmark rather than a personalized record for any single kitchen table, but it illustrates how persistent price pressures erode the baseline value of cash.
Why a growing balance can still lose value
A helpful way to examine a savings account is to treat the deposit as a bucket that holds stored purchasing power. The interest credited by a financial institution acts like a small faucet, trickling additional dollars into the bucket at set intervals. At the same time, inflation acts as an opening near the base, steadily draining the real purchasing capacity of whatever dollars remain inside. If the outflow created by rising prices moves faster than the trickle from the faucet, the water level of actual buying power drops, even while the total number of paper dollars counted in the bucket increases.
This dynamic shapes basic saving decisions. Interest can increase the numerical size of a cash deposit, but inflation reduces what that deposit can purchase when withdrawn. Because these two forces work in opposite directions, the final outcome depends entirely on how the pace of price increases compares to the interest credited over that exact timeframe. Educational materials from Federal Reserve Education on interest rates frame this tension as the primary reason why tracking dollar amounts alone gives an incomplete picture of financial security.
The problem deepens when wages and household income fail to keep pace with broader price increases. If monthly paychecks remain flat while utility bills and shelf prices tick upward, families are forced to redirect more of their income toward immediate operating costs. That leaves less room to add new deposits to savings in the first place, compounding the quiet decay of the cash already sitting idle in an account.
Nominal rates versus real rates
Making sense of this erosion requires separating the interest rate displayed on an account statement from the rate that governs real-world buying power. The posted annual percentage yield or interest figure is the nominal rate. It states the exact percentage gain in raw currency units over a year. A nominal rate tells a saver how many dollars will be added to the principal, but it offers zero information about whether those dollars will buy more or fewer goods when the period ends.
The real interest rate adjusts that stated figure for inflation. It reflects the genuine gain or loss in purchasing capacity that a depositor experiences over time. The St. Louis Fed offers an educational breakdown of adjusting for inflation to illustrate how headline figures can disguise changes in real economic outcomes. Consider a general, hypothetical example: if an account earns three percent in nominal interest over twelve months, but the prices of goods and services rise by five percent over that same stretch, the real return is roughly negative two percent. The balance grew on paper, but the owner can purchase two percent fewer real items with the resulting total.
This distinction also explains why inflation affects borrowers and lenders in sharply different ways. A borrower repaying a fixed-rate loan during periods of high inflation may repay the debt with dollars that are worth less than when the money was originally borrowed. A lender, or an individual saver depositing cash in an institution, sits on the opposite side of that ledger. When the real rate turns negative, the depositor effectively absorbs the purchasing power loss, while the borrower experiences a lighter real repayment burden.
Where the data ends and personal tracking begins
Standard educational summaries describe the broad relationship between rates and prices, but they do not provide personal balance calculations or recommend specific financial products. Government agencies do not tell individuals where to store their emergency reserves or promise that any specific cash vehicle will outpace general price hikes. Cash reserves serve practical purposes, such as covering unexpected car repairs or medical bills, regardless of the inflation rate in any single quarter.
To see how historical price shifts have affected the dollar's value over multi-year spans, savers can use the official BLS CPI inflation calculator. The tool allows users to enter a dollar amount from a past year and see what sum would be required to equal that purchasing capacity in a later period. Exploring these public tools helps ground the concept of purchasing power in historical facts, showing that the value of stored cash is never static, even when the account balance looks steady on paper.


