 Credit Score Education
 Credit Reporting & Consumer Rights
 Personal Finance Tips
 Budgeting & Money Management
 Identity Theft & Fraud Prevention
 Credit Card Education
 Consumer Financial News
 Cost of Living & Inflation
 Banking & Savings Education
 Consumer Protection & Financial Literacy

It is the 8th, rent is due tomorrow, and a utility payment is still pending. A low-balance alert might give you a chance to check the calendar before another withdrawal arrives. It cannot predict every charge or replace a budget, but it can add a timely prompt to a routine you already use.
Why balance awareness matters for overdraft fees
An overdraft or non-sufficient funds (NSF) fee may apply when a checking account does not have enough money to cover a transaction. The Consumer Financial Protection Bureau estimated that customers of banks and credit unions paid about $15 billion in overdraft and NSF fees in 2019. That is a national estimate from that year, not a current fee total or a forecast for any one account.
The CFPB also reports that people with lower balances or less predictable income and expenses may face hundreds or even thousands of dollars in these fees over a year. A bill can be manageable on its own and still create a shortfall if several withdrawals cluster together. The CFPB says low-balance alerts can help people know when they may be at risk of overdrawing, and encourages tracking account balances carefully.
Put recurring payments on a calendar first
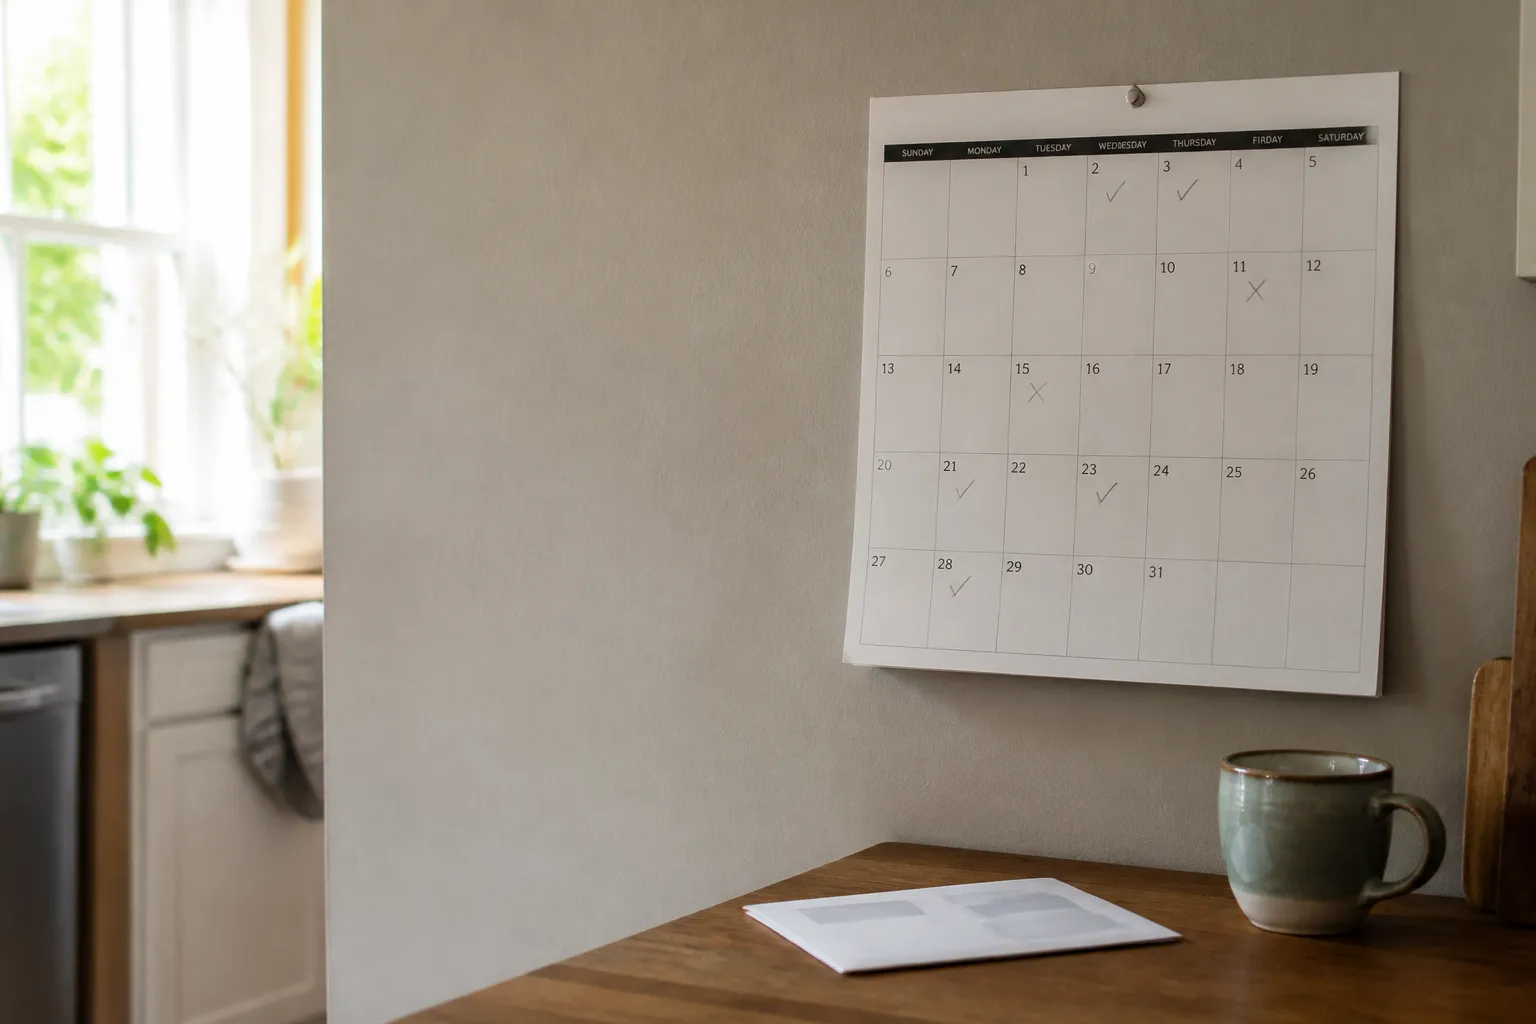
Before choosing an alert threshold, make a calendar of regular electronic transfers. Include the payment name, expected amount, and date it usually occurs. Mortgage payments and utility bills are common examples. The CFPB recommends knowing the amount and timing of recurring transfers so you can plan around them.
Then look for the tight spots. If a large payment is due shortly before payday, that interval may deserve more attention than a quiet week. A balance alert can serve as a prompt to review what is scheduled, rather than as a guarantee that a payment will clear without a fee. Posting dates and balances can vary, so check how your institution describes them and keep some room for timing differences when possible.
Automatic transfers can also support savings goals, according to MyCreditUnion.gov. They also become another calendar item to account for. A savings transfer that happens just before a bill may affect the balance available for that bill, so include it in the same view of your regular cash flow.
Choose alerts that answer a useful question
Alert menus vary by institution. Ask whether your bank or credit union offers low-balance alerts, and where to find the settings on its official website or app. You can also ask whether it offers alerts for deposits or large transactions, and how those alerts are delivered. The available sources do not establish which alert types every institution provides or whether a notice arrives by text, email, or app notification.
A useful alert should prompt a specific check. For example: “Is the utility payment still expected today?” or “Did the scheduled deposit arrive?” If an institution lets you choose a balance threshold, consider how it relates to the payments on your calendar. A threshold set too low may come after a risky stretch has begun; one set too high may produce frequent notices that are easy to ignore. The right setting depends on your account activity and the options your institution offers.
When you enable an alert, confirm the selected condition and the contact details associated with it. Ask whether there can be a delay between an account event and its notification. If frequent alerts become background noise, check whether settings can be adjusted rather than relying on notices you no longer notice.
Compare backup arrangements before a shortfall
An alert can flag a problem, but it does not add money to an account or stop a scheduled payment. Some institutions allow a checking account to be linked to savings so funds can transfer to cover an overdraft. The CFPB says that transfer usually has a fee, though it is generally lower than a standard overdraft fee. The transfer can still cost money, and it may affect the savings balance you meant to keep for another purpose.
Some institutions also offer an overdraft line of credit. The CFPB says its fee is usually lower than a per-item overdraft fee, but interest is charged on the borrowed amount. That means the cost depends on both fees and how much is borrowed and for how long. These arrangements differ, so ask your institution to explain the fees, interest, and terms before deciding whether an option fits your needs.
Useful questions include whether low-balance alerts are available, whether checking can be linked to savings, and what fees or interest apply to any overdraft coverage. The CFPB’s guidance on avoiding debit card overdrafts explains that consumers can decline debit card overdraft coverage or cancel it if they previously opted in. Under that setting, a debit card transaction without enough funds may be declined instead of paid with an overdraft fee.
Review patterns and verify current terms
Repeated overdraft or NSF fees can signal financial strain and may contribute to an account being closed, according to the CFPB. If alerts repeatedly arrive around the same bill dates, use that pattern as a reason to review the calendar, payment timing, and account activity. An alert is a warning, not a judgment about why a shortfall happened.
Fees and account terms can change. The FDIC consumer page on overdraft and account fees is dated December 2021, so confirm current costs directly with your bank or credit union. The CFPB’s research on consumer experiences with overdraft programs provides background on how these fees affect account holders.
Alerts are one part of keeping a bill calendar current. They may help bring a low balance or an unexpected transaction to your attention, but they do not set spending limits or guarantee that every transaction will be noticed in time. For broader budgeting tools and consumer education, visit the CFPB’s official resources and check your own institution’s current alert and account terms.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


